 BBBAccredited Business
Kaminskiy Care and Repair rebuilds commercial and multi-unit property after water damage or another covered loss, once the area is dry: drywall and ceilings, insulation, flooring, cabinets, trim and paint. For an insurance restoration we first write a line-item scope with photos the owner can hand to the adjuster, then supply completion photos. We do not adjust claims or promise coverage. Drying and mold remediation belong to licensed specialists. A leak still running is leak and shut-off valve repair. Loss repairs sit inside our commercial remodeling and restoration services.
A failed supply line on the third floor wets three stacked units. Once the leak is stopped and the drying company has pulled its equipment, each unit needs drywall, insulation, base, flooring and paint, and often a vanity or sink base. We scope each unit separately so the owner, the association and each insurer can see their own lines.
A roof or plumbing leak above a ceiling stains tile, soaks carpet and swells the bottom of drywall and cabinets. The tenant needs to reopen. We replace damaged drywall, lift and replace flooring, rebuild casework and repaint, phased so the unaffected part of the suite keeps working. Stained grid ceilings are handled as drop ceiling tile replacement.
After a small kitchen fire or a car into a storefront wall, specialists clean smoke, board up and make the building safe, and an engineer signs off on any framing question. Our part begins there: rebuilding the non-structural walls, cabinets, counters, flooring and finishes. Storefront glass goes to a glazier.
We photograph every affected room wide and close, measure walls, floors and cabinets, and note the moisture readings from the mitigation report if you have it.
Each room gets its own list: quantity, material and task per line, with like-kind finishes named. The owner sends it to the adjuster, and we answer the adjuster's questions about the repair itself.
Framing repairs and insulation, drywall and texture, paint, then flooring, cabinets, trim and hardware. Units stay locked, neighbors get notice, and debris leaves daily.
Completion photos matched to the scope lines, a signed completion form if your carrier uses one, and upgrades the owner selected shown on their own lines.
The EPA advises drying water-damaged areas and items in 24 to 48 hours to prevent mold growth, and notes that porous materials such as ceiling tile and carpet may have to be discarded once moldy. That is why mitigation comes first and why we check that framing is dry before closing a wall. For visible growth beyond roughly 10 square feet, the EPA points owners to its commercial building guidance, and that cleanup is specialist work, licensed in some states.
States regulate who can negotiate a claim for a policyholder. In Texas, for example, the Department of Insurance says a contractor may not act as a public insurance adjuster on a claim for property it is repairing, and may not offer to waive or absorb a deductible. Rules differ by state. Our practice everywhere is the same: we describe the damage and the repair, and the owner and the adjuster settle the claim.
Mold remediation is a licensed activity in some states. Texas requires a state license to remediate visible mold of 25 contiguous square feet or more and does not let one company both assess and remediate the same project. Florida licenses individual mold remediators. Where your state has such a rule, the licensed remediation firm finishes and clears the area before our rebuild starts.
Sources for the rules on this page: U.S. EPA, A Brief Guide to Mold, Moisture and Your Home; U.S. EPA, Mold Remediation in Schools and Commercial Buildings Guide, Chapter 4, Table 1; Texas Department of Insurance, Roofing and insurance: Know the law; Texas Department of Licensing and Regulation, Mold Assessors and Remediators FAQ; Florida Department of Business and Professional Regulation, Mold-Related Services FAQ.
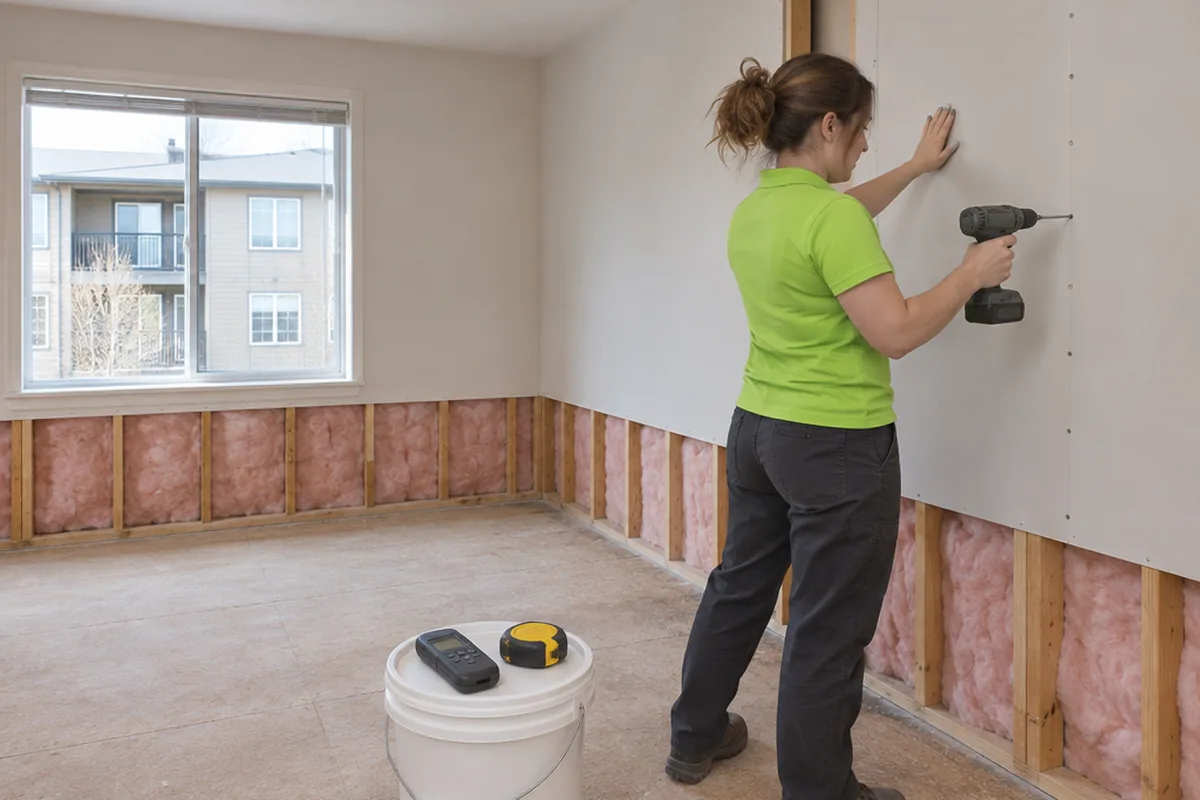
Water damage repair on drywall starts after the leak is stopped and the cavity is dry. We cut out wall board and ceiling sections that are stained, swollen or soft, back to the center of sound framing, pull wet insulation and check the framing with a moisture meter before closing. New board is hung, taped, finished, textured to match and sealed with a stain-blocking primer so the old mark does not bleed through the paint. EPA guidance for commercial buildings allows wallboard wet with clean water to be dried in place only when it shows no obvious swelling and its seams are intact; otherwise it is removed and replaced. Visible mold beyond a small area goes to a licensed remediation company before we rebuild.
Flooring and casework take water differently from walls. Soaked carpet pad and laminate flooring are normally replaced, glued vinyl may lift at the seams days later, and a wood subfloor is checked for soft spots before any new floor goes down, as our subfloor repair page describes. Particleboard cabinet bases and vanity floors swell and do not recover, so we rebuild the damaged panel or replace the box and reset the counter. Each item is written as its own line under its room, so an owner can see exactly what the water reached.
Many leaks are repaired without a claim. A stained ceiling under a unit bath or a strip of wall behind a sink is often smaller than the deductible, and the owner simply wants it closed. The repair is the same without the claim paperwork: stop the source, confirm dry, cut out, rebuild, prime and paint. We still photograph the open cavity and the finished surface, because a dated record of what was wet and what was replaced is useful if the same spot leaks again or the unit changes hands.
Adjusters read line items, quantities and photos. We write the repair that way from the first walk, then build exactly what was written.
Every loss gets the same three documents. A room-by-room scope with quantities and like-kind materials. A photo set, wide and close, labeled by room and tied to the scope lines. A completion file with after photos and a sign-off. Supplements for damage found behind a wall are written and photographed before that work is done, never after.
Most of these are paperwork gaps as much as repair gaps. A line-item scope with photos usually moves the file. We write it and build it. The claim itself stays between you and your carrier.
Send the loss address, the mitigation report if there is one, and the adjuster's estimate if you have it.
We document the damage and return a line-item scope and price you can forward to the adjuster.
Once you approve, we rebuild in sequence and hand over completion photos tied to each line.
The work is backed in writing by our workmanship warranty and done by a Kaminskiy-certified, background checked technician.
Mitigation stops the damage: water extracted, wet material cut out, air movers and dehumidifiers run until readings are dry. Repair puts the building back. They are separate jobs, often separate invoices on the claim. Ask the mitigation firm for its final moisture readings and a sketch of what it removed. That report is the starting point of our scope and tells us the framing is ready to be closed.
Property policies generally pay to restore what was there. If the unit had laminate counters, the estimate carries laminate. An owner who wants solid surface can have it, and we show the difference as a separate upgrade line that the owner pays. Keeping upgrades off the claim lines keeps the file clean and the adjuster's review short. Your policy and your adjuster define what applies to you.
A loss rarely respects room edges. Half a floor is wet, one wall of a painted room is replaced, two base cabinets in a run are swollen. We note in the scope where a repair will not match the undamaged remainder, with photos, so the owner can raise it with the adjuster. Whether continuous flooring or a full repaint is owed is the carrier's decision, not ours.
Hidden damage is normal: wet insulation behind dry-looking board, a rotted sill plate, a subfloor that crumbles under the old vinyl. When we find it, work on that item stops. We photograph it, measure it and write a supplement line. The owner forwards it and approves it before we proceed. A supplement that arrives with photos and measurements is far easier for a carrier to review than a larger invoice at the end.
Can't find your answer? Call 855-695-1195 and ask us anything.
Call 855-695-1195Yes, as the repair contractor. We give the adjuster a line-item scope, photos, measurements and answers about how the repair is done. We do not negotiate the settlement or speak for you on coverage. States regulate who may do that for a policyholder.
No. Coverage depends on your policy and the cause of loss, and that reading belongs to your carrier, your agent or a licensed public adjuster. What we can do is describe the damage accurately, separate old wear from new damage in the photos, and price the repair so the decision is made on facts.
No. Extraction, drying equipment and any mold remediation are done by mitigation and remediation specialists, licensed where the state requires. We begin when the area is dry and cleared. If you call us first, we will tell you plainly that a mitigation firm comes before us.
Work on that area stops. A small patch on a surface we are already removing is bagged and discarded with the board. Anything larger, or growth inside a cavity, goes to a licensed remediation company, and we return when they have cleared the area in writing.
That is the aim, and it depends on texture and paint. We match the existing texture across the patch, seal any remaining stain with a stain-blocking primer, and repaint to a natural break such as a corner. Aged paint rarely matches from a touch-up, so we say in the scope where a full wall or ceiling needs a coat.
Our agreement is with the owner or the manager who signs the scope. How the claim payment reaches you, and what the deductible and depreciation are, is between you and your carrier. Upgrades the owner chooses beyond like-kind repair are listed as separate lines.
We stop that item, photograph and measure what we found, and write a supplement line with a price. You send it to the adjuster and approve it before we continue. Nothing hidden is repaired and added to the bill afterwards without that step.
Line by line: each task has a quantity, a material and a labor amount, by room. That format lets an adjuster compare our scope with the carrier's estimate and see where they differ. The total depends on the area affected, the finishes being matched, access, and how many units or suites are involved.
Yes. A stacked water loss often involves three or four units plus a corridor. Each unit gets its own scope and photo set, because the owner's policy, the association's policy and the residents' policies may each cover different parts. We schedule the units together so trades move floor to floor.
Send the address, what happened and when, the mitigation report and the adjuster's estimate if you have them, and photos. A line-item scope follows our walk. Or call 855-695-1195.
A line-item scope. The rebuild in sequence. A completion file for the claim.
We answer in under three rings, 24/7.No price games. You get a clear written quote before any work begins, backed by our workmanship warranty.